Plumber Insurance in Massachusetts: Coverage Every Pipefitter Needs
Plumber insurance in Massachusetts: what you need to stay protected
If you run a plumbing business in Massachusetts, plumber insurance is not a formality you can skip. One water-damage claim from a burst pipe you worked on, one injured apprentice, one stolen van full of tools, and an uninsured plumber can lose everything they built. The right coverage is straightforward to understand and, for most solo operators and small shops, more affordable than people expect.
Why plumbers face unique insurance risks in Massachusetts
Plumbing work puts you inside people's homes and commercial buildings, working with systems that can cause serious, expensive damage when something goes wrong. A slow leak behind a wall can rot framing, destroy drywall, and trigger mold remediation bills running into the tens of thousands of dollars. A water-heater installation that fails can flood an entire finished basement. These are not edge cases; they are the everyday liability reality for any plumber operating in the Pioneer Valley or anywhere else in the state.
Massachusetts has its own regulatory environment that shapes your insurance requirements. The state's Board of State Examiners of Plumbers and Gas Fitters oversees licensing for journeyman and master plumbers, and many municipalities and general contractors require proof of insurance before you can pull a permit or step on a job site. Getting licensed without the right coverage in place puts that license at risk.
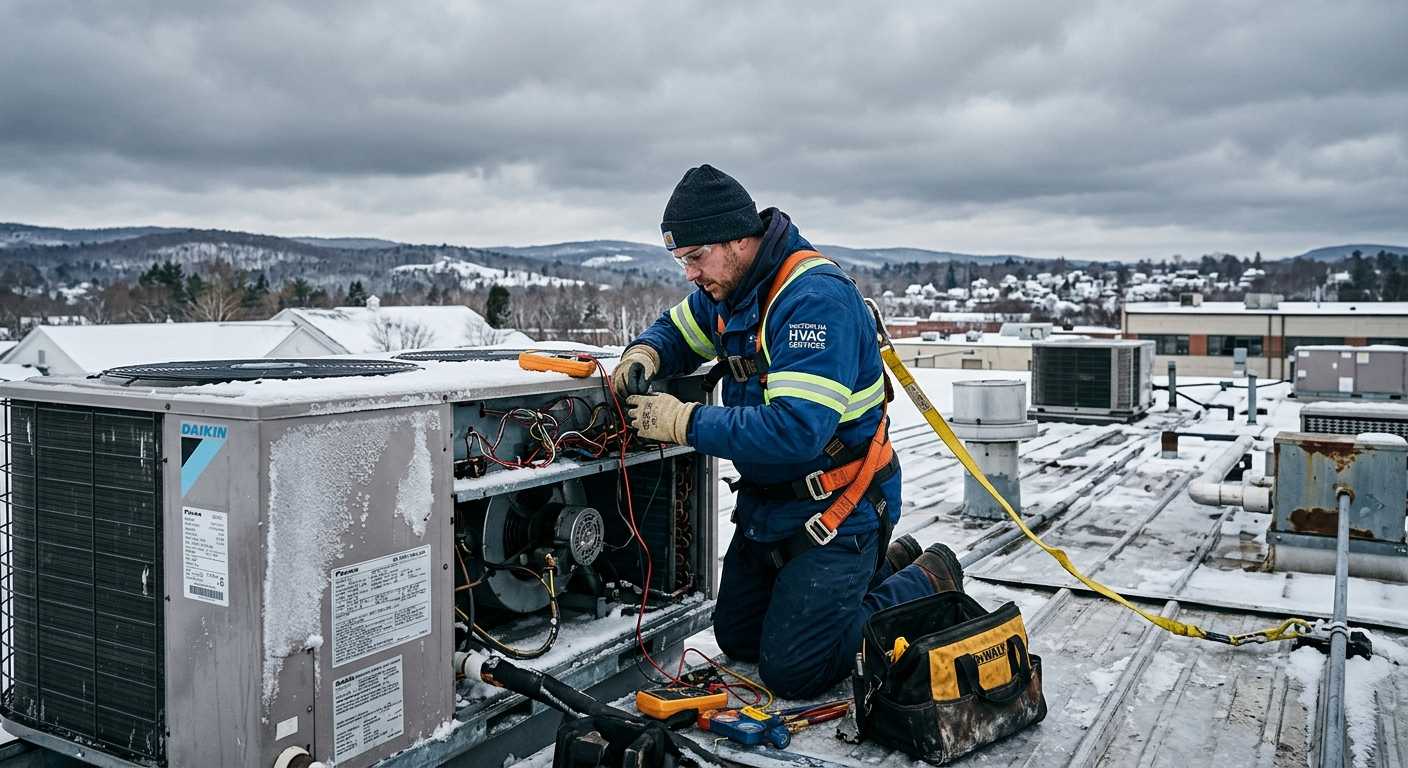
Weather adds another layer. Western Massachusetts winters are hard on plumbing systems, which means plumbers here often work in cramped crawl spaces, icy driveways, and frozen basements. Those conditions raise the chance of on-the-job injuries and property incidents.
Core coverages every plumbing contractor needs
Think of your insurance program as a stack of protections, each layer handling a different category of risk. Most plumbing businesses in Massachusetts need all of the following.
General liability insurance
General liability (GL) is the foundation. It covers third-party bodily injury and property damage claims arising from your work. If you accidentally crack a supply line during a bathroom renovation and water damages a homeowner's hardwood floors, GL pays for the repair. If a customer trips over your toolbox and files a medical claim, GL responds. Most GC contracts and permit applications require a minimum of $1,000,000 per occurrence / $2,000,000 aggregate . Learn more about how this coverage works on our general liability insurance page.
Workers' compensation insurance
Massachusetts law requires workers' compensation for any business that has employees, with almost no exceptions. Even one part-time helper means you must carry it. The penalty for non-compliance includes fines of up to $250 per day and a stop-work order that shuts your jobs down immediately. For sole proprietors with zero employees, coverage is technically optional, but if you are injured on a job without workers' comp, your medical bills and lost income come entirely out of pocket. Rates for plumbers are based on your payroll and your claims history. Our post on workers' compensation insurance in Massachusetts walks through how rates are calculated.
Commercial auto insurance
Your work van or truck is not covered by a personal auto policy the moment you are using it for business. Massachusetts requires at minimum $20,000/$40,000 in bodily injury liability and $5,000 in property damage for any registered vehicle, but those state minimums are far too low to protect a business. A commercial auto policy gives you higher limits, covers your tools and equipment in the vehicle to a basic degree, and can add coverage for hired or non-owned vehicles if your crew sometimes drives their own cars to job sites. See our commercial auto page for more detail.
Inland marine insurance (tools and equipment)
Standard commercial property policies cover property at your business location. Inland marine insurance covers your tools and equipment wherever they go, which for a plumber means job sites, vehicles, and customer properties. A pipe threading machine, press-fit tools, diagnostic cameras, and a full van of fittings and supplies can easily represent $15,000 to $40,000 in equipment. Inland marine fills the gap that other policies leave open. You can review our inland marine coverage page for specifics.
Commercial umbrella insurance
A standard GL policy pays up to its limits, then stops. If a major water-damage claim exceeds your GL limit, or if a serious injury lawsuit pushes past your auto liability limit, a commercial umbrella picks up where those underlying policies end. For plumbers working on larger commercial projects or multifamily housing, umbrella limits of $1,000,000 to $5,000,000 are increasingly common contract requirements.
Optional but often important coverages
Depending on your business model, some additional coverages deserve a closer look.
Professional liability (errors and omissions)
If a client claims your work design or your advice was faulty, general liability may not cover it. Professional liability insurance , sometimes called E&O, covers claims that your professional judgment or recommendations caused financial harm. Plumbers who do design-build work, consult on system specs, or work on complex commercial systems benefit from this coverage.
Builders risk insurance
If you are the general contractor on a project, or if your contract makes you responsible for the structure during construction, builders risk covers damage to the building under construction. Even as a sub, some contracts push this responsibility to you. Our builders risk page explains how the coverage works and when you need it.
Surety bonds
Many Massachusetts homeowners and commercial clients ask for a contractor's license bond or a performance bond before hiring a plumber. A bond is not insurance in the traditional sense; it is a guarantee that you will complete the work as promised. If you fail to perform, the bond pays the client and you reimburse the bonding company. For plumbers working on public projects or bidding on municipal contracts in cities like Springfield or Holyoke, bonds are often mandatory.
How much does plumber insurance cost in Massachusetts?
Cost depends on several factors: how many employees you have, your annual revenue and payroll, the types of jobs you take (residential vs. commercial, new construction vs. service and repair), your claims history, and the carriers available to your broker. Ballpark ranges for small to mid-sized plumbing operations in Massachusetts are below.
- General liability: $900 to $2,500 per year for a sole operator; $3,000 to $7,000+ for a shop with employees and higher revenue.
- Workers' compensation: typically $5 to $12 per $100 of payroll for plumbers in Massachusetts, depending on classification codes and experience modifier.
- Commercial auto: $1,200 to $2,800 per vehicle annually for a work van with commercial limits.
- Inland marine / tools: $300 to $800 per year for most small operators.
- Commercial umbrella: $500 to $1,500 per year for a $1,000,000 umbrella layer over underlying policies.
Bundling coverages, keeping a clean claims record, and working with an independent agent who can shop multiple carriers are the most reliable ways to keep your total premium reasonable.
Massachusetts licensing and insurance: what the state requires
Massachusetts issues several license classes for plumbers. A master plumber's license is required to pull permits and run a plumbing company; journeyman plumbers must work under a master. The Board of State Examiners of Plumbers and Gas Fitters does not mandate a specific insurance minimum at the state level for licensure, but local building departments and general contractors do. The most common requirements you will encounter on job sites in Northampton, Chicopee, Amherst, and across the Pioneer Valley are:
- Proof of general liability: usually $1,000,000/$2,000,000 minimum, with the property owner or GC named as an additional insured.
- Certificate of workers' comp: the Massachusetts Department of Industrial Accidents (DIA) requires a certificate of insurance before issuing most permits.
- Valid auto insurance: registration and permit inspections may require proof of commercial auto.
Getting a certificate of insurance (COI) from your agent is a routine request. A good agent can issue one quickly when a new job requires it.
What plumbers often get wrong about their coverage
A few common mistakes show up repeatedly when plumbers review their policies.
- Relying on a personal auto policy for the work van: personal auto policies exclude business use. A claim filed after a work-related accident can be denied entirely.
- Skipping tools coverage: neither your van nor the homeowner's property coverage protects your equipment. Inland marine is the correct policy for this.
- Not updating payroll estimates: workers' comp premiums are based on estimated payroll. If your business grows and you add people mid-year, your policy can be audited and you may owe a significant additional premium at year-end.
- No additional insured endorsements: general contractors and property owners frequently require that they be named as an additional insured on your GL policy. If you do not add them when required, you can lose the contract or be held in breach.
- Gaps in completed operations coverage: GL policies cover damage that happens while you are on the job, but completed operations coverage extends protection to claims that arise after the job is done. A slow leak that shows up six months later still needs to be covered.
Get the right plumber insurance for your Massachusetts business
Family Insurance Group is an independent insurance agency serving plumbers and pipefitters across western Massachusetts, including Springfield, Holyoke, Northampton, Chicopee, Amherst, and the surrounding communities. As an independent agency, we work with multiple carriers, which means we compare rates and coverages on your behalf rather than selling you one company's product. That matters when you are trying to build a complete, correctly structured policy at a price that makes sense for your business.
Our team understands the trades. We know what job-site contracts require, what the state expects, and where plumbing businesses tend to be underinsured. You can visit our plumbers and pipefitters insurance page to see the coverages we typically build for plumbing contractors, or reach out directly to start comparing your options.
Call us at (413) 416-1234 or get a quote online and we will put together a program that covers your tools, your vehicles, your crew, and the work you are proud of.
Get A Quote
At Family Insurance Group, securing your future is easy. Ready to protect what matters? Contact us for a quick quote and personalized insurance options!
Kelly
Speak to Kelly 24/7
Microphone ready
Start your custom insurance quote
Instant answers to your insurance questions
Schedule appointments or follow-ups
Personal Insurance
From auto and homeowners to renters and umbrella policies, we help protect your family and property. Let’s find coverage that fits your life.
Commercial Insurance
We customize policies for your industry's risks, like general liability and workers' comp, ensuring you can run your business worry-free.
Contact Family Insurance Group
Recent Posts